September 2026 DVC Field Guide Resale Market Update
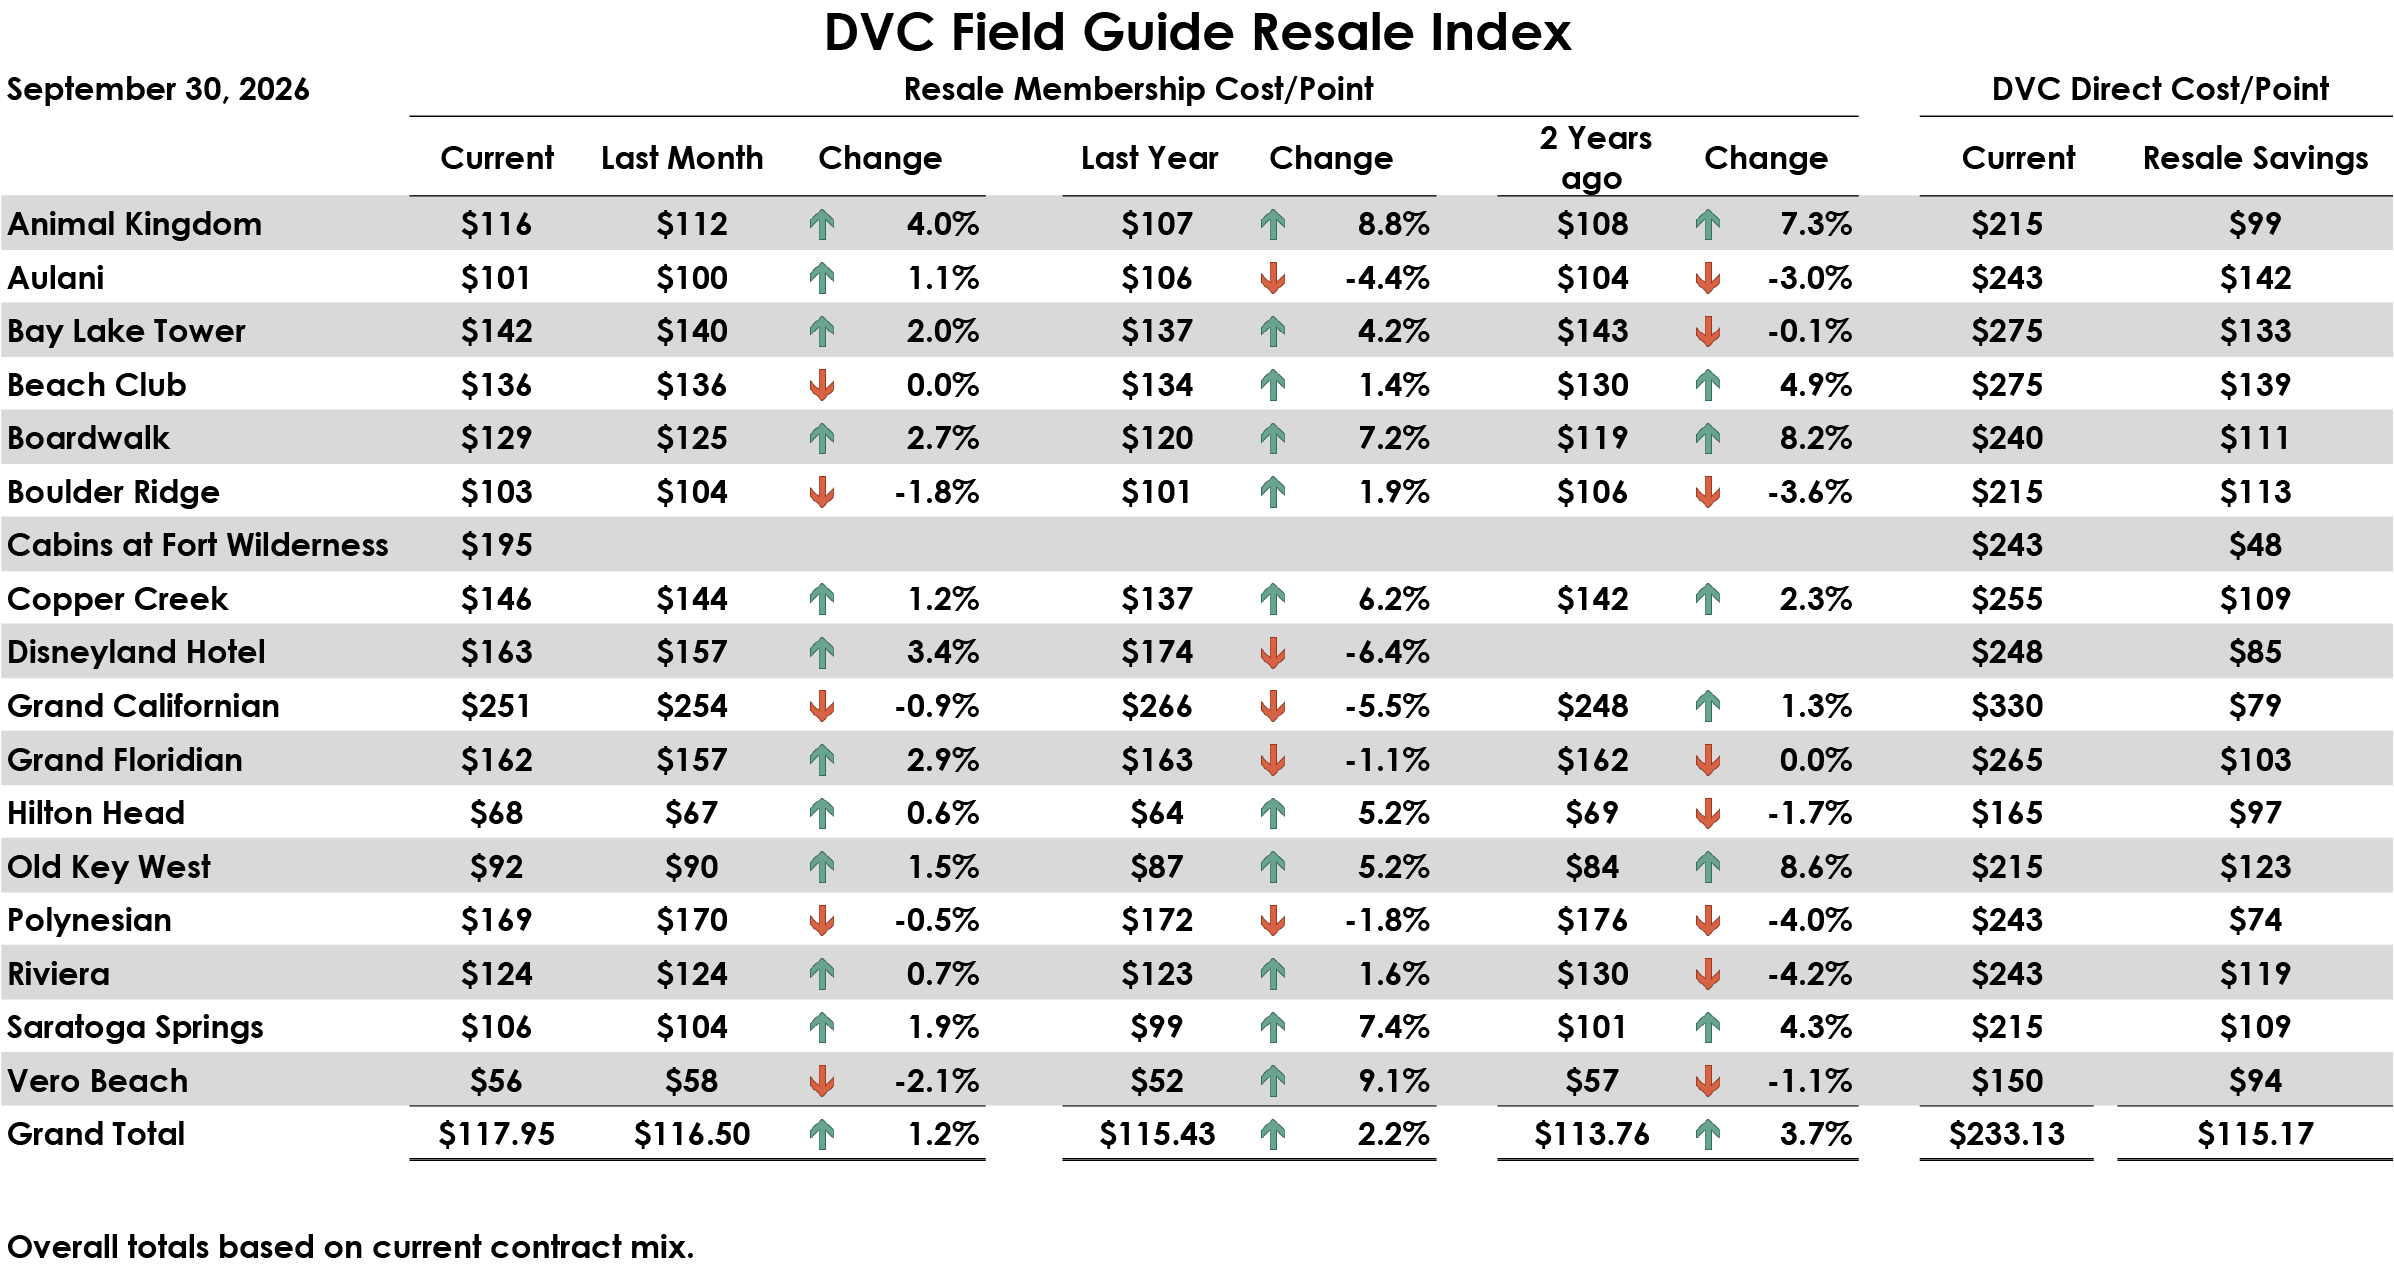
The September 2026 DVC Field Guide Resale Index rose to $117.95 per point, up from $116.50 in August. That represents a 1.2% monthly increase and places the index 2.2% above September 2025 and 3.7% above September 2024.
The September increase continues a broader pattern of stability within the Disney Vacation Club resale market. Although individual resort prices continue to move from month to month, the blended index remains within a relatively narrow range. Resale values have generally strengthened during the past year even as the number of available contracts has fallen substantially.
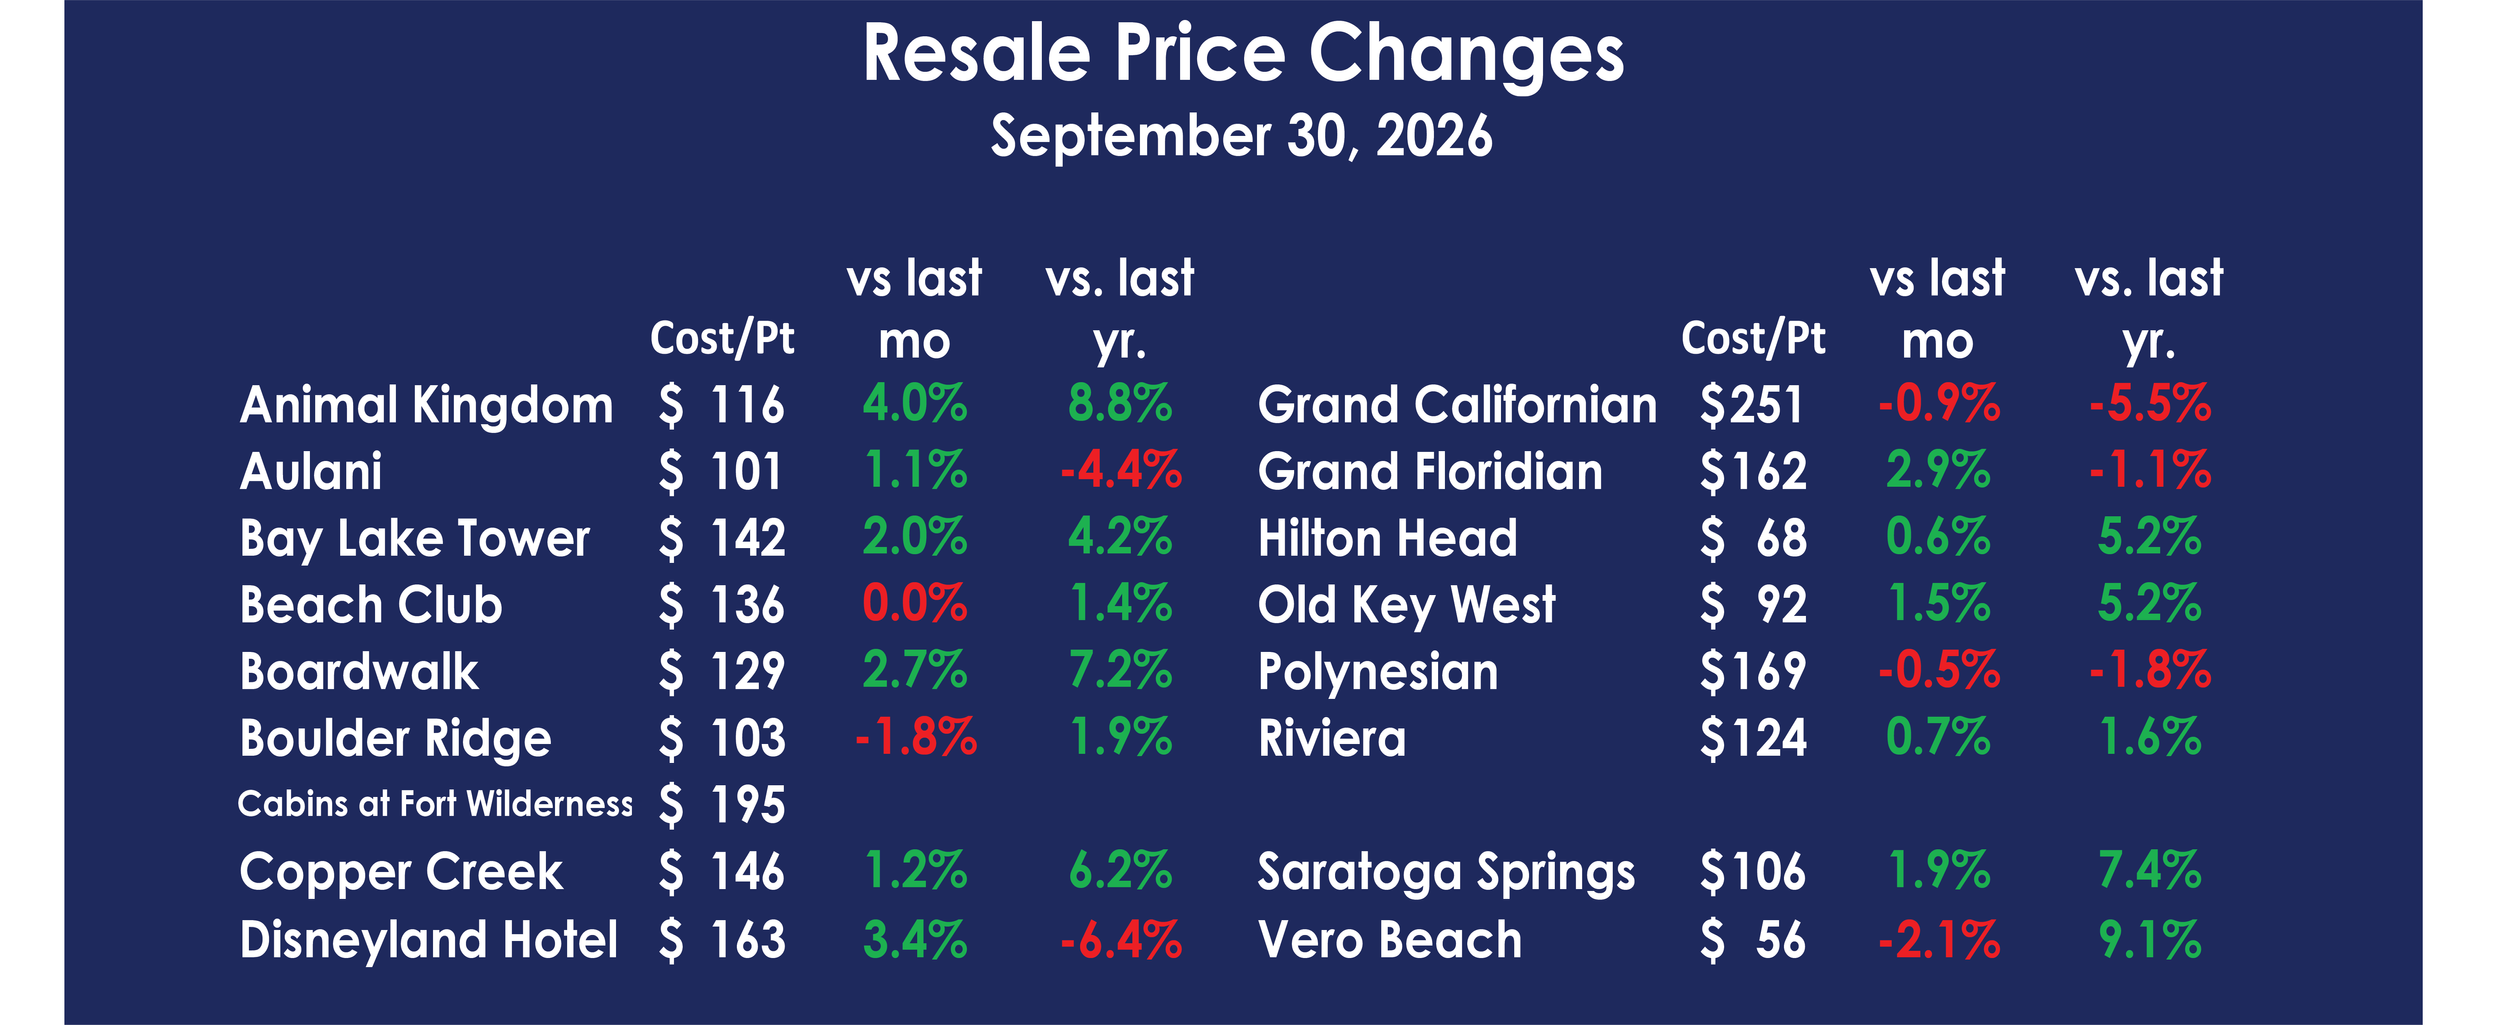
Several resorts contributed to September’s increase. Animal Kingdom rose from $112 to approximately $116 per point, a monthly increase of 4.0%. Disneyland Hotel increased 3.4% to approximately $163, Grand Floridian gained 2.9% to $162, BoardWalk increased 2.7% to $129, and Bay Lake Tower rose 2.0% to $142. Saratoga Springs also increased 1.9%, reaching approximately $106 per point.
The September results were not universally higher. Vero Beach declined 2.1% to approximately $56 per point, while Boulder Ridge fell 1.8% to $103. Grand Californian decreased 0.9% to $251, and Polynesian declined 0.5% to $169. Beach Club remained essentially unchanged at approximately $136 per point.
Over the past year, the strongest increases occurred at Vero Beach, Animal Kingdom, Saratoga Springs, and BoardWalk. Vero Beach increased 9.1%, Animal Kingdom rose 8.8%, Saratoga Springs gained 7.4%, and BoardWalk increased 7.2%. Copper Creek was also up 6.2%, while Hilton Head and Old Key West each increased approximately 5.2%.
The largest year-over-year declines were concentrated among the California resorts. Disneyland Hotel fell 6.4%, while Grand Californian declined 5.5%. Aulani decreased 4.4%, Polynesian fell 1.8%, and Grand Floridian declined 1.1%. These decreases do not necessarily represent weakening demand across the entire market. Resort averages can be influenced by the size, point availability, Use Year, and asking prices of the relatively small number of contracts available at a particular time.
Resale Inventory Remains Well Below Prior Years
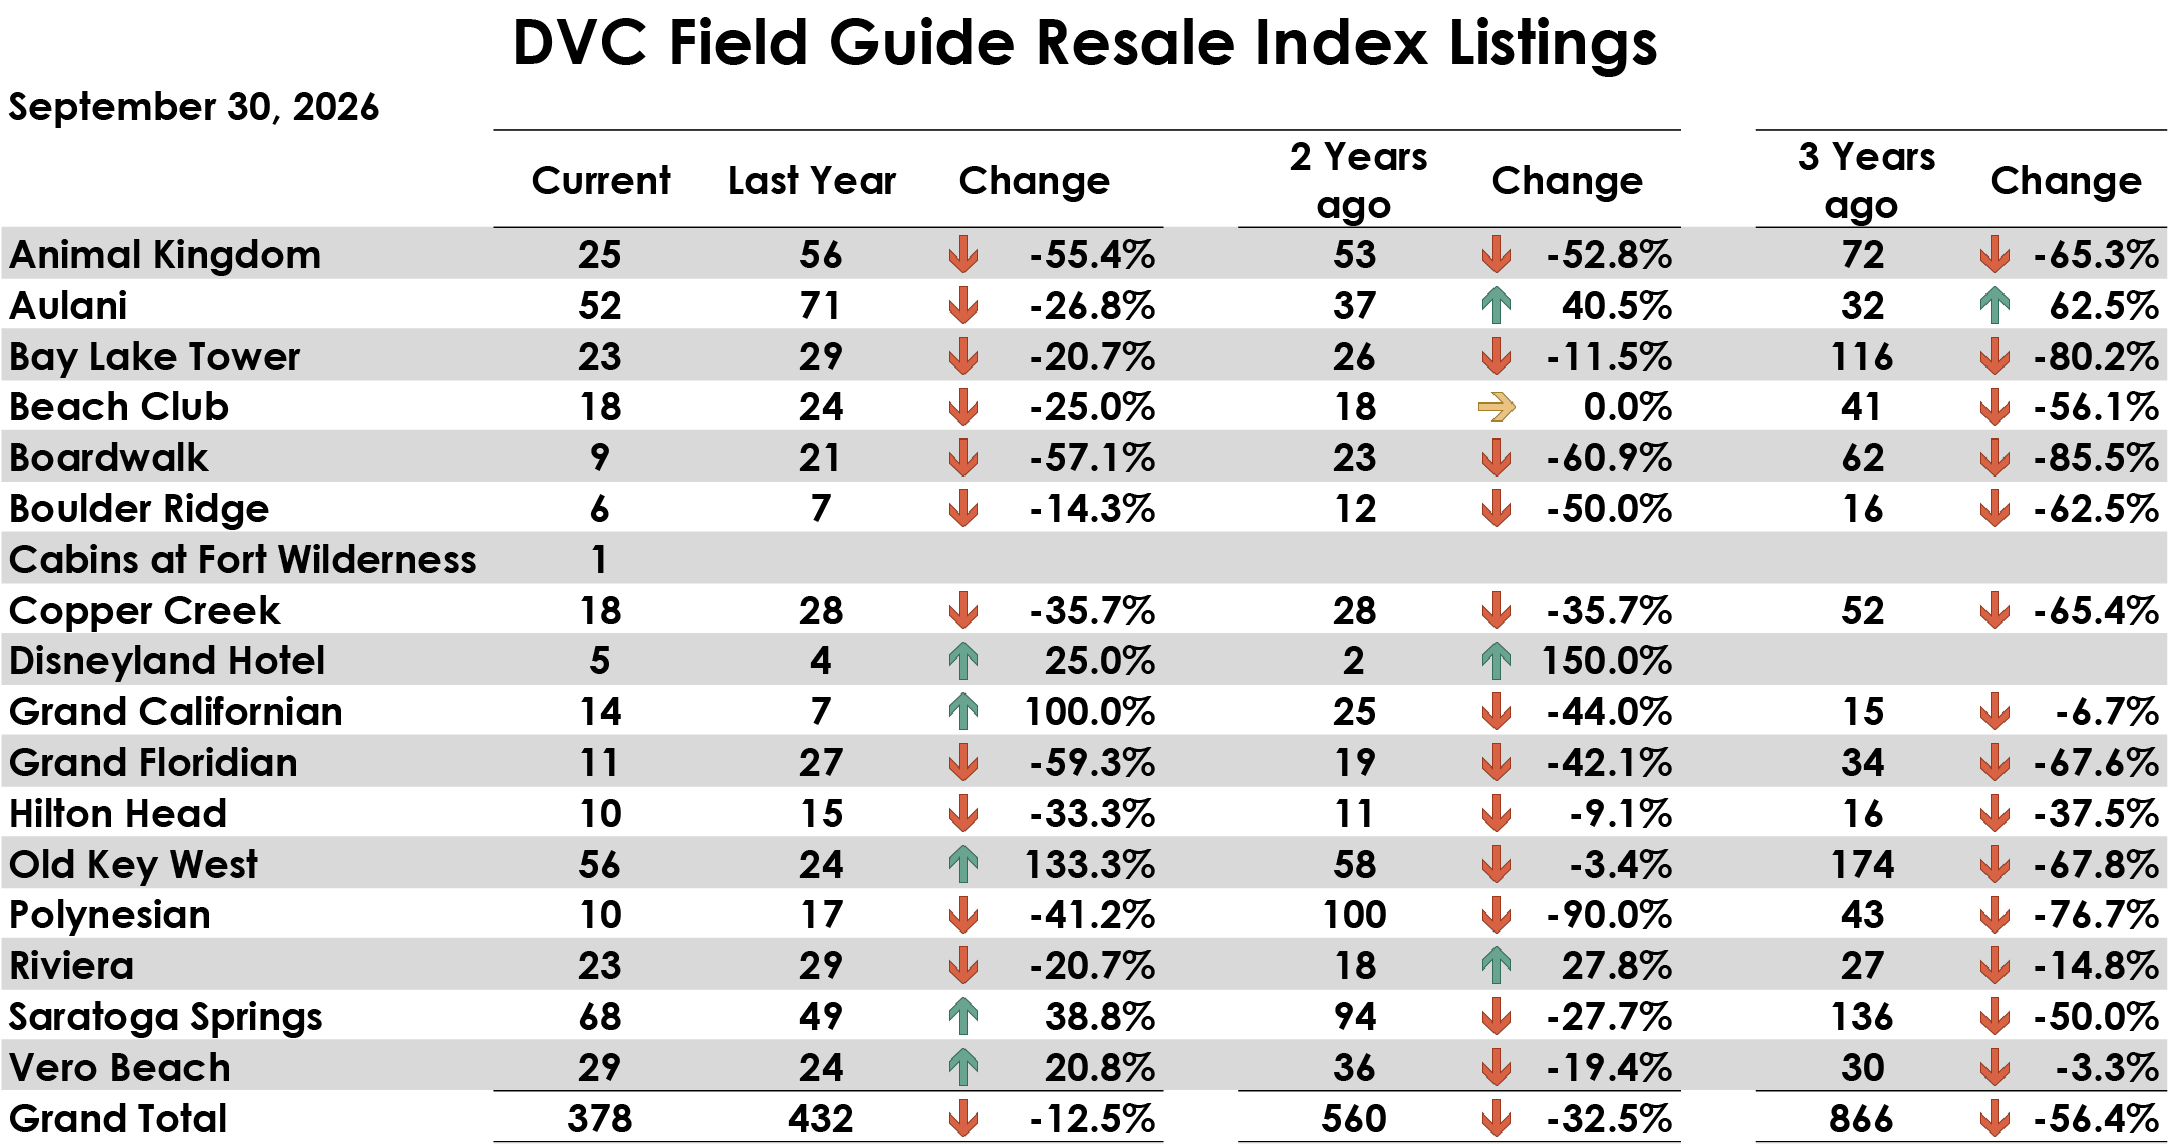
There were 378 resale contracts included in the September inventory count, compared with 432 contracts one year ago. That represents a year-over-year decline of 12.5%. Inventory was also 32.5% below September 2024 and 56.4% below September 2023, when the same brokers carried 866 listings.
The overall decline becomes even more significant when the distribution of the available inventory is considered. Saratoga Springs accounted for 68 listings, Old Key West for 56, and Aulani for 52. Together, those three resorts represented nearly 47% of all contracts included in the September count.
Inventory remained particularly limited at several popular resorts. Only nine BoardWalk contracts, six Boulder Ridge contracts, five Disneyland Hotel contracts, and one Cabins at Fort Wilderness contract were included. Grand Floridian had 11 listings, Polynesian had 10, and Grand Californian had 14.
Old Key West experienced the largest year-over-year inventory increase, rising from 24 to 56 listings. Saratoga Springs increased from 49 to 68, Grand Californian rose from seven to 14, and Vero Beach increased from 24 to 29. These increases were outweighed by substantial declines elsewhere. Grand Floridian inventory fell 59.3%, BoardWalk declined 57.1%, Animal Kingdom fell 55.4%, and Polynesian decreased 41.2%.
Compared with three years ago, the contraction remains dramatic. Bay Lake Tower inventory is down 80.2%, BoardWalk is down 85.5%, Polynesian is down 76.7%, and Old Key West is down 67.8%. The total number of listings has fallen from 866 to 378 during that period.
This continuing reduction in supply helps explain why the overall resale index has remained firm. Buyers have fewer contracts from which to choose, particularly at resorts with smaller ownership bases or strong Home Resort demand. At the same time, the concentration of listings at Old Key West, Saratoga Springs, and Aulani means that the broader inventory total can overstate the number of realistic choices available to a buyer seeking a specific resort.
Resale Savings Compared with Direct Pricing
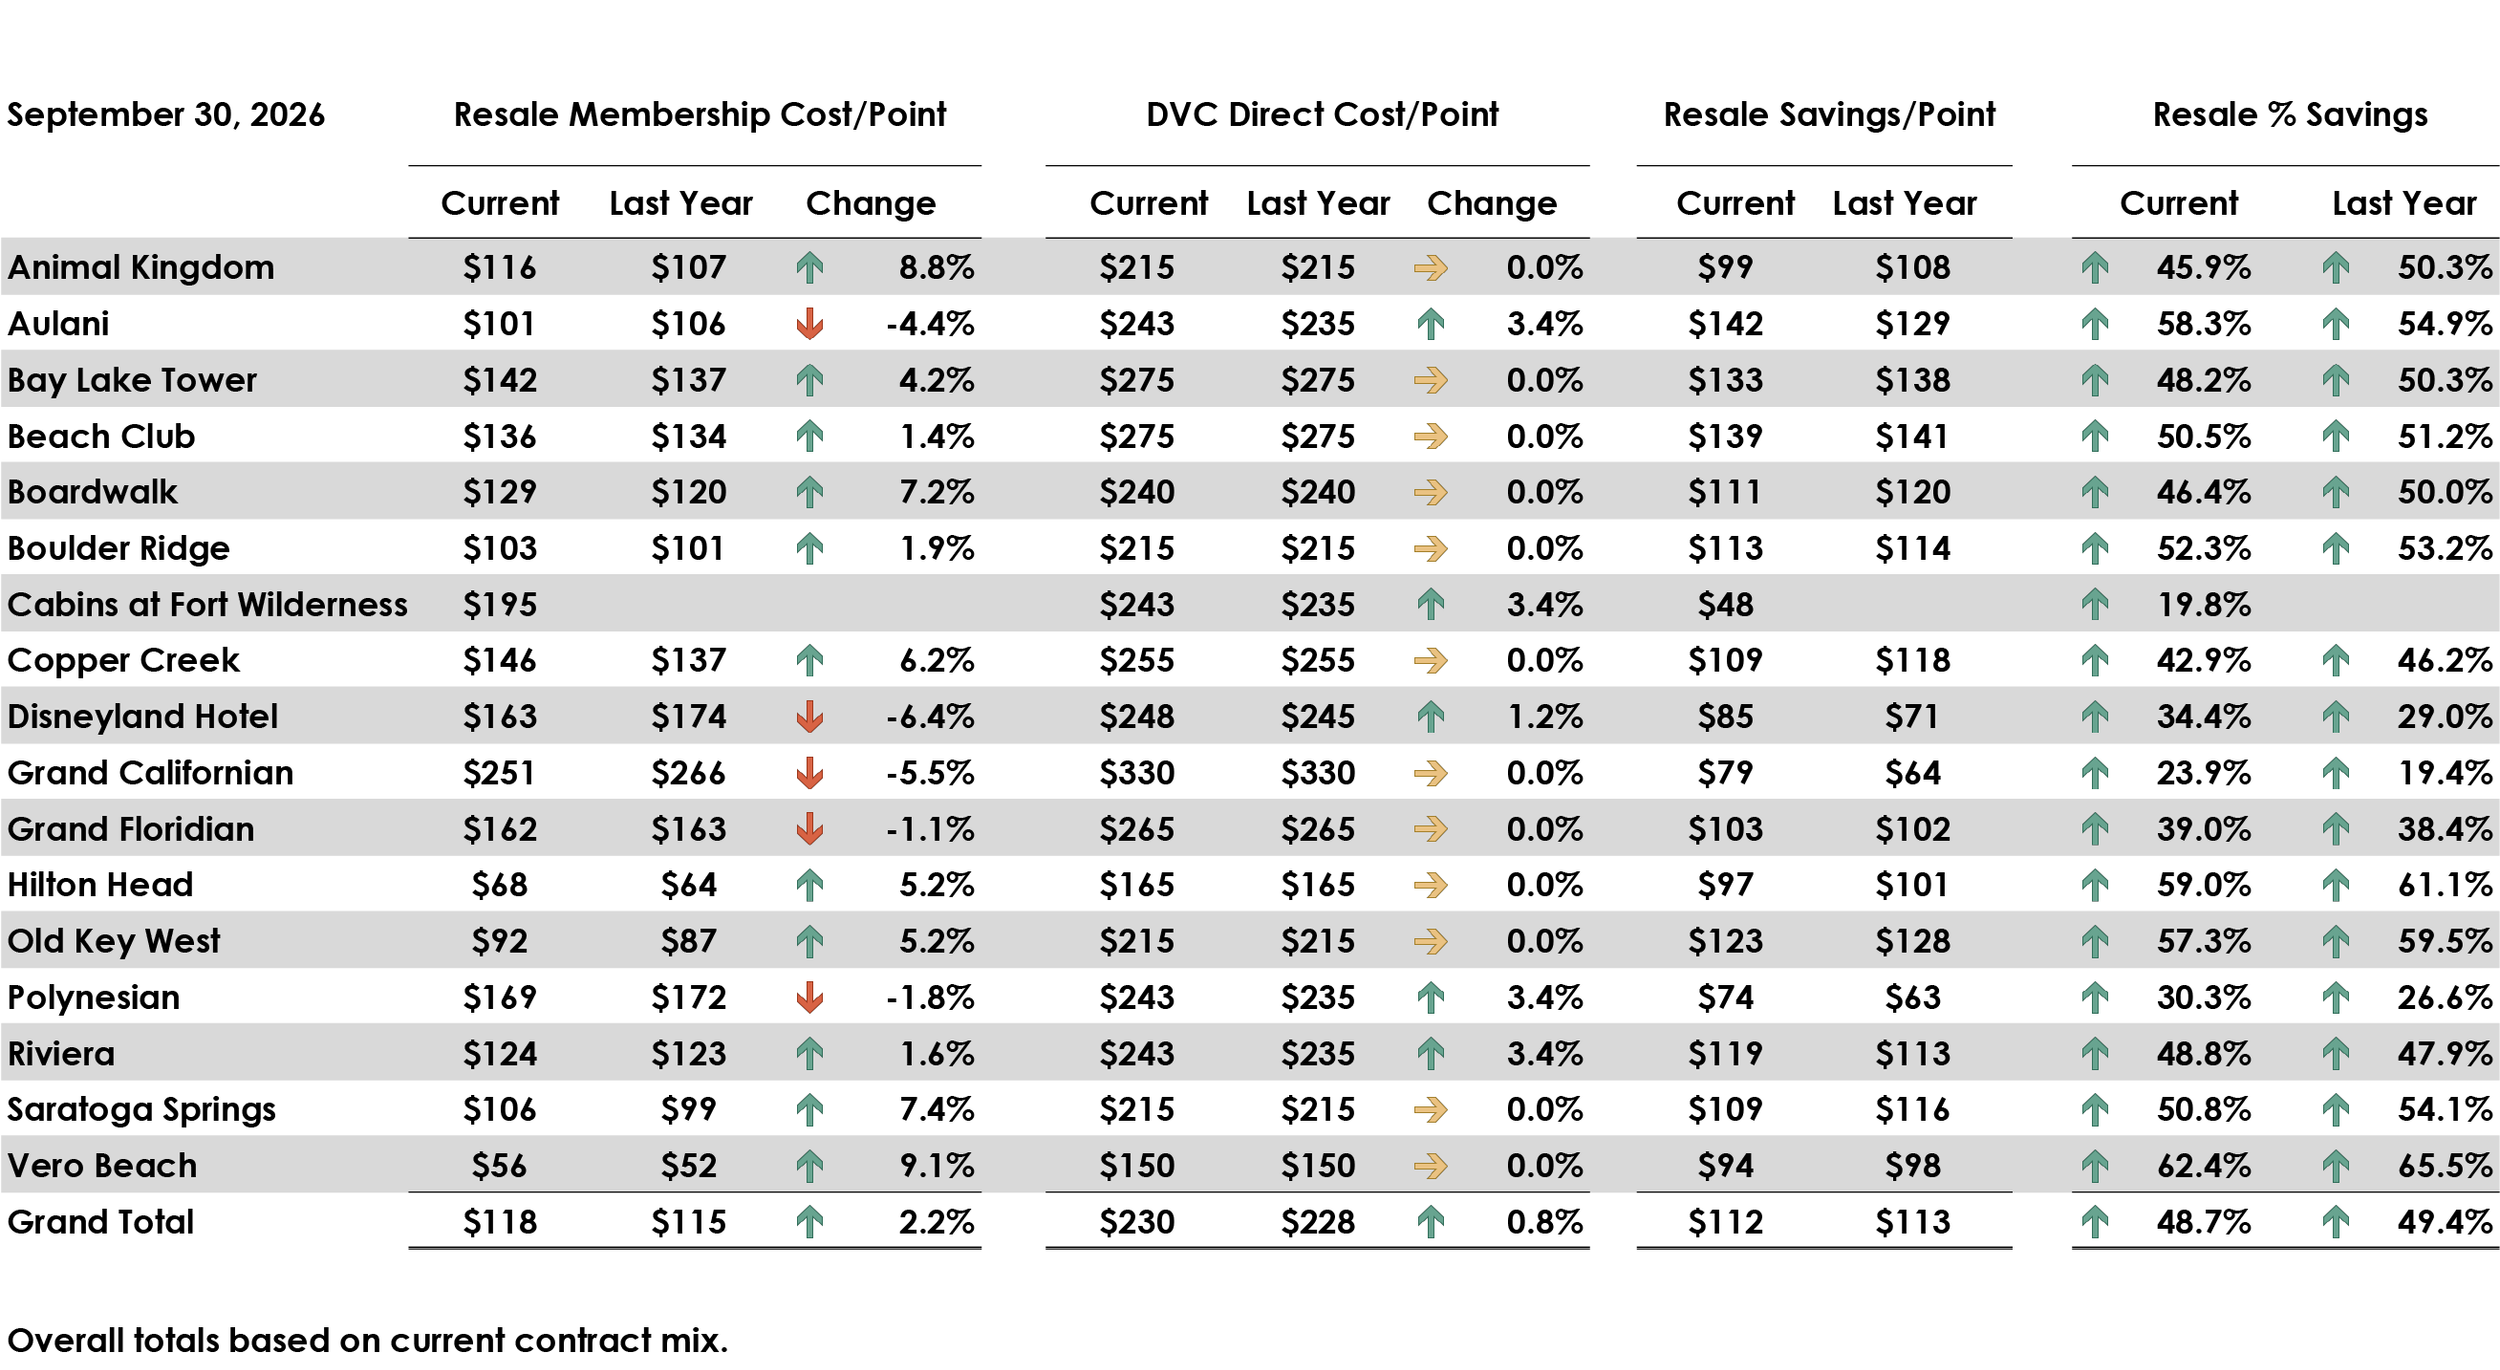
Based on the current mix of contracts, the average DVC direct price was approximately $233.13 per point, compared with a resale average of $117.95. The resulting average savings was approximately $115.17 per point, meaning resale prices were nearly 49% below direct pricing.
The largest dollar savings were found at Aulani, where the difference between the $243 direct price and the $101 resale average was approximately $142 per point. Beach Club provided savings of approximately $139 per point, Bay Lake Tower $133, Old Key West $123, Riviera $119, and Boulder Ridge $113.
Vero Beach provided the largest percentage discount, with resale pricing approximately 62.4% below direct pricing. Hilton Head followed at 59.0%, Aulani at 58.3%, Old Key West at 57.3%, and Boulder Ridge at 52.3%. Beach Club and Saratoga Springs were each available at approximately half their respective direct prices.
The smallest resale discount belonged to the Cabins at Fort Wilderness. Its $195 resale price was only $48 below the $243 direct price, producing savings of approximately 19.8%. Grand Californian provided savings of approximately 23.9%, while Polynesian offered a discount of approximately 30.3%. These resorts may still provide meaningful savings, but their resale discounts are considerably smaller than those available at many of the older DVC properties.
Purchase Price and Annual Dues
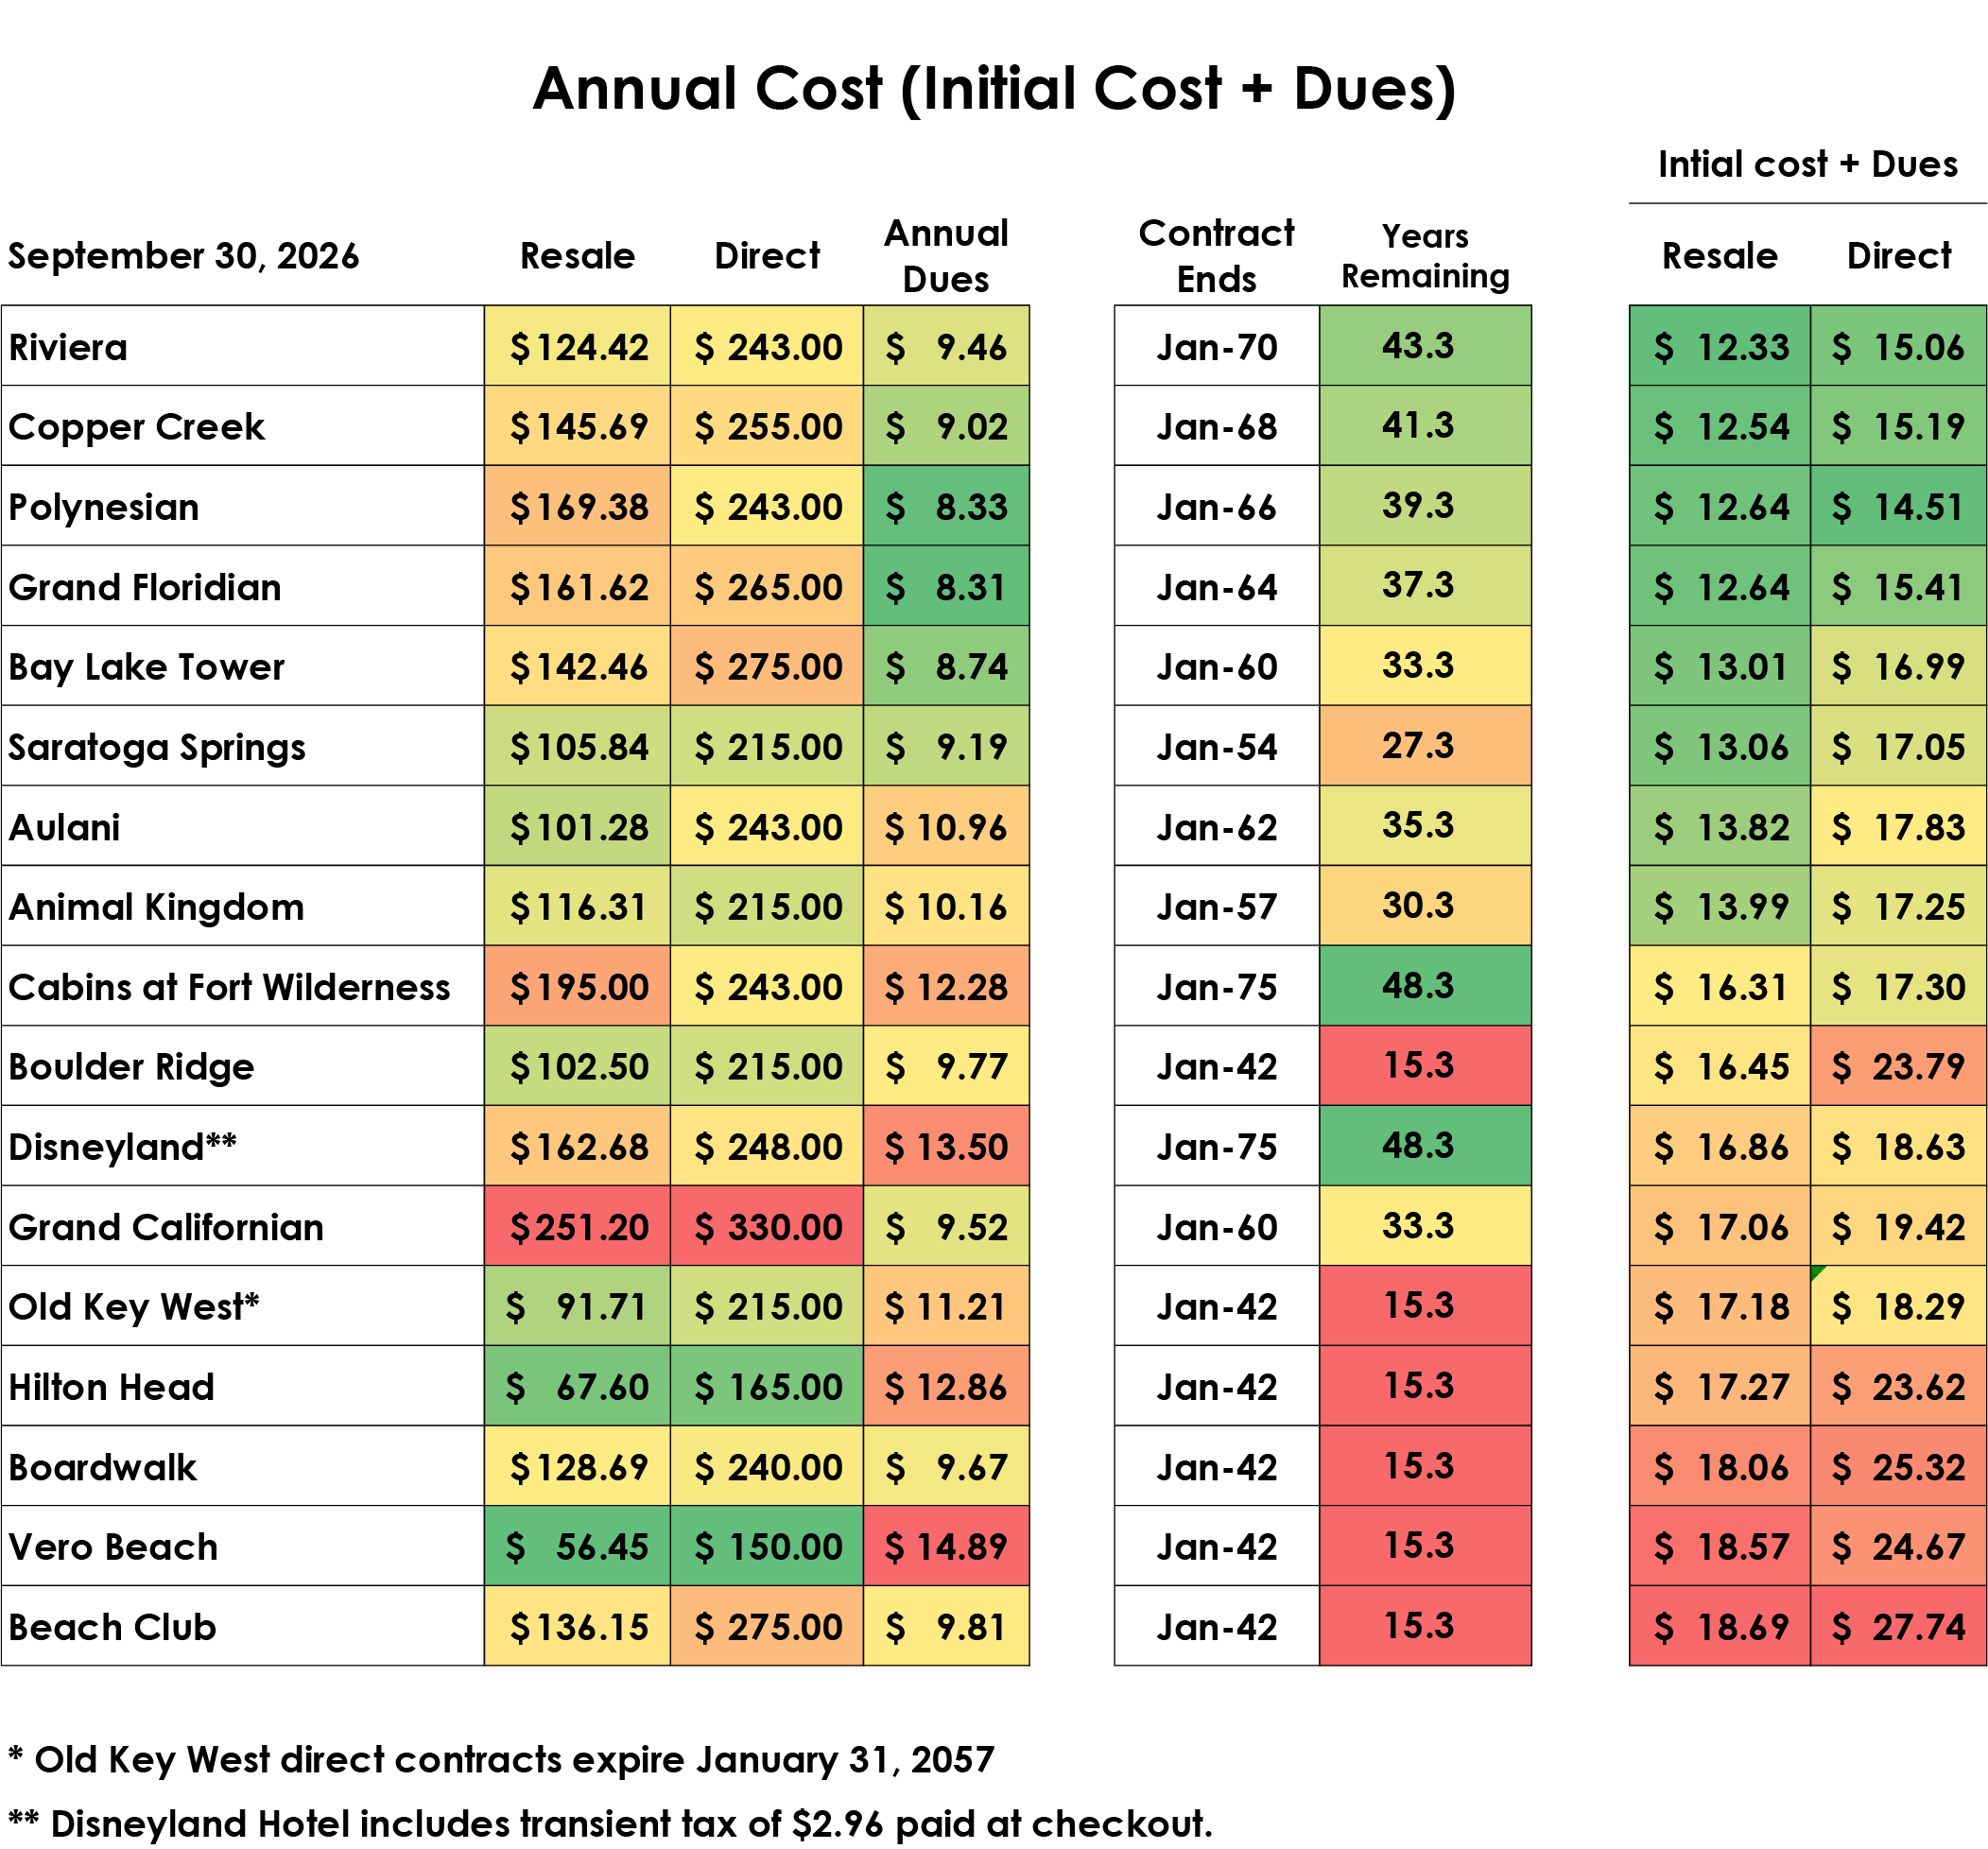
Purchase price alone does not provide a complete picture of long-term ownership cost. The DVC Field Guide annual-cost comparison combines the initial purchase price, spread across the remaining years of the contract, with current Annual Dues.
Using this method, Riviera had the lowest estimated annual resale cost at approximately $12.33 per point, followed by Copper Creek at $12.54. Polynesian and Grand Floridian were each approximately $12.64, Bay Lake Tower was $13.01, and Saratoga Springs was $13.06.
These results illustrate the value of a longer contract. Riviera, Copper Creek, Polynesian, and Grand Floridian have higher resale purchase prices than several older resorts, but their remaining contract life allows the initial cost to be distributed across more years.
The 2042 resorts generally ranked near the bottom of the annualized resale comparison because their purchase prices must be recovered over approximately 15 remaining years. Beach Club had the highest estimated annual resale cost at $18.69 per point, followed by Vero Beach at $18.57, BoardWalk at $18.06, Hilton Head at $17.27, and Old Key West at $17.18.
The Cabins at Fort Wilderness have one of the longest contracts, but their combination of a relatively high resale price and Annual Dues of $12.28 produced an estimated annual cost of $16.31 per point. That placed the Cabins behind several resorts with shorter contracts and lower Annual Dues.
The annual-cost comparison should not be interpreted as identifying one universally superior Home Resort. Booking priority, room preferences, point charts, contract restrictions, expiration dates, Annual Dues, and likely vacation patterns must also be considered. However, it provides an important reminder that a low purchase price does not always result in the lowest long-term ownership cost.
September Market Perspective
September produced a comparatively strong monthly increase in the DVC Field Guide Resale Index, but the larger story remains the market’s stability. The index is now 2.2% higher than it was one year ago despite considerable differences among individual resorts.
The persistent shortage of available contracts continues to support resale pricing. Although total inventory increased at several resorts, the market still contained 54 fewer listings than it did one year ago and 488 fewer than it did three years ago. Buyers have significantly fewer choices, while sellers at popular resorts face less competition than they did during the inventory-heavy market of 2023.
Resale continues to provide substantial savings compared with purchasing directly from Disney, but the size of that advantage varies widely. The September data reinforces the importance of evaluating each resort individually. Purchase price matters, but so do Annual Dues, contract length, booking priority, point requirements, resale restrictions, and the way the Membership will actually be used.
Overall, the September results describe a resale market with limited inventory, stable-to-rising blended prices, and meaningful long-term savings compared with direct purchasing. The market is not moving uniformly, but the continuing decline in available contracts has helped resale values remain resilient as 2026 enters its final quarter.
About the DVC Field Guide
The DVC Field Guide is an independent resource for current and prospective Disney Vacation Club members, providing in-depth analysis of resale pricing, historical trends, annual dues, ownership costs, and booking availability. Its monthly market indexes track resale activity from the three largest Disney Vacation Club resale brokers—DVC Resale Market, Fidelity Real Estate, and The Timeshare Store—to provide an objective view of market conditions.